Showing posts with label rates. Show all posts

Monday, January 10, 2011

Switzerland: Swiss Franc -ly Under Attack

Separate reports this week in the Swiss newspaper Neue Zuericher Zeitung (NZZ) are highlighting the difficult choices Switzerland, and by extension other nations, are facing in the continued onslaught of effective currency devaluation by US and Eurozone officials. The Greenback and the Euro have fallen significantly against the Franc and other currencies in the past years as their governments and central banks have created a glut of supply; by loosening monetary policy, lowering interest rates and creating massive amounts of new debt to bail out ailing banks, businesses and governments.   The choices for nations such as Switzerland are clear:  Reduce living standards and income values through inflation, or see a massive outflow of jobs and industry from their borders. 

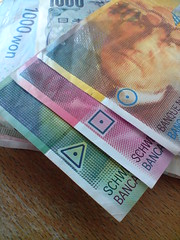
Swiss Banknotes by kalleboo
The Swiss National Bank (SNB) has announced losses of 8.5bil Swiss Francs in the first 3 quarters of 2010, resulting from their foreign exchange interventions intended to curb the effect of the inflating Euro and Greenback on their economy.  These losses stem from the SNB's massive selling of Swiss Francs and purchasing of Euros in order to simultaneously increase market supply of Swiss Francs to lower it's exchange rate; and increase competition in the Euro-dollar market to help support/increase its value.  Despite these efforts and the losses thereof, the Eur/Chf (Euro/Swiss Franc) exchange rate has fallen from late 2007 highs of 1.68 to current levels of 1.25.  This has had a severe effect on Swiss industry, most of whom must repatriate sales made in the Eurozone in order to book profits.  This peak to trough fall represents a loss to Swiss exporters of 0.43 Chf in every dollar they earn, or roughly 0.25 in aggregate terms.

Such extreme cuts to profits have Swiss industry chiefs remarking that in current conditions they cannot consider new hiring or expanding production in Switzerland, and making controversial threats to move jobs out of Switzerland and into the Eurozone, where wages have dropped along with the Euro relative to the Swiss Franc.  Retailers are also complaining that more and more Swiss shoppers are travelling the short distance to make their purchases accross the border, which is not far from any point in the small landlocked Alpine country.  The tourism industry is also feeling the pinch, as it is more expensive for Europeans to buy Francs.  Some doubt the long term viability of small and mid-sized businesses in Switzerland if the Franc's value to the Euro cannot be stabilised above 1.30.  The NZZ this week specifically quoted Georges Hayek, chief of Swatch-Group and Hans Hess, president of Swissmem, an association representing the mechanical and electrical engineering industry, as calling for government intervention in this regard.

However, such government intervention would in all cases amount to a rapid inflation of the Swiss currency.  This would cause prices of goods to rise generally, affecting the value and purchasing power of all Swiss incomes, from wage-earners to business owners to pensioners.  The Swiss authorities thus face a double-edged sword:  To take action is to lower living standards for all Swiss residents and cut the value of savings; to hold firm is to risk a general flight of industry and jobs and support a loss of value in local stock market investments.  In all cases jobs, savings and investments are threatened.  This dilemma is at the root of the murmurrings of currency war surrounding the G20 meetings in Seoul, which saw the US and Europe insisting that China allow the yuan to rise, and China along with Brasil, Korea and a host of other nations from across the globe complaining of the ill-effects to their economies caused by the effective devaluatoin of the Euro and Dollar by Western central banking authorities. 

Just as the European central bank (ECB) was forced to bail out Greece and Ireland by helping to create new money, and is currently fighting to prop up the Portuguese national budget with bond purchases, so are Federal authorities in the US now facing calls to bail out hopelessly indebted states and municipalities.  The Wall Street Journal reports that Federal Reserve chairman Bernanke has scuttled such talk by pointing out that new rules under the Dodd-Frank laws enacted by the federal government last year limit the fed`s ability to intervene should states or municipalities go into default/bankruptcy.  Such issues in Europe and America will, regardless of how they are addressed, create more instability in foreign exchange markets, to the detriment of economies outside their borders; from first world economies such as Switzerland, Canada and Japan, down to China, Brasil, India and all others dependent on the global economic model. 

Read more:

German Language Sources:
http://www.nzz.ch/nachrichten/wirtschaft/aktuell/tiefer_euro_gefaehrdet_wohlstand_1.8958738.html
http://www.nzz.ch/nachrichten/politik/schweiz/schweiz_nationalbank_verlust_85_milliarden_franken_2010_1.8356119.html

Other English Language Reports on the Swiss Franc and US Debt:
http://online.wsj.com/article/SB10001424052748704739504576067602380461160.html
http://online.wsj.com/article/BT-CO-20101112-701368.html
http://www.swissinfo.ch/eng/specials/swiss_franc/Strong_franc_continues_to_haunt_Swiss_economy.html?cid=17955460

Thursday, November 18, 2010

Seoul G20: Perplexing Conclusion, Clear Result

The conclusion of the most recent G20 summit in Seoul last Friday, hailed as a success for political reasons by attending politicians, was punctuated with the following agreed upon statement: "Uneven growth and widening imbalances are fueling the temptation to diverge from global solutions into uncoordinated action... uncoordinated policy actions will only lead to worse outcomes for all."  In other words, 'while we agree in principal that it is best to agree, we disagree.'  I can only imagine that, if only the leaders of nations in times past, who with the specter of wars and economic strife looming before them, had been privy to such wisdom, things would have turned out exactly the same...

In spite of ambiguous political statements made in Seoul last week, markets have been remarkably unified in their response.  Since markets closed on the Wednesday (Nov. 10) before the summit began in earnest, every single major US dollar denominated market has fallen.  Several of these markets had been gaining steadily leading up to the G20 summit, but all have dipped in response to the G20's conclusion.  Here is a quick statistical rundown of some of those losses up to the Wednesday Nov. 17 close:

Dow Jones   -350 points (-3.1%);
S&P 500   -40 points (-3.2%);
NYSE Comp.   -259 points (-3.3%)
Crude $/Brl   -6.77 (-7.7%)
Copper $/lb   -0.24 (-6.0%)
Gold $/oz   -62 (-4.4%)
Platinum $/oz   -97 (-5.6%)


Thus, money (or value) is coming out of stock and commodity markets across the board.  Furthermore, Treasuries, both 30yr and 5yr notes, fell 1.5% and 0.9% respectively, during the same period; markets which often gain when stock markets are in turmoil.  Taken in the context of a rise of 1.44 points (+1.9%) during the same period, in the US Dollar Index (USDX) which is a guage of the value of the dollar relative to other world currencies, we can reasonably assume that losses in the value of stocks and commodities are partly, if not mainly, a result of a strengthening US dollar.  This represents deflation.  What is the cause of this deflationary pressure?  It could be that investors have responded to the G20's failure to resolve its differences over state manipulations in currency markets by pulling out of markets and deleveraging, or paying off debts.  The US dollar being a debt-based currency, any net reduction in USD debts effectively reduces the amount of USD in the system, producing deflation. 

Perhaps the dirtiest word in modern economics, many analysts of late, even Fed chief Bernanke, have begun to broach the issue of deflation.  That it is impossible in America has been the misplaced hope of so many bank and fund chiefs.  The Japanese banking crisis of the 1990s has resulted in persistent deflation for over a decade.  The more recent global recession, particularly the crash in the summer of 2008, was a deflationary crash, which saw all markets lose value at break-neck speed after being inflated by Bush's bank bailouts and stimulus spending.  That extra money was un-created nearly as quickly as it was created when it was used by large institutions to pay off debts and deleverage.  So what to expect?  With interest rates already at historical lows and failing to stimulate more borrowing, look for the Federal Reserve to enact more quantitative easing, the modern equivalent of printing money.  This will complete another round in the cycle, and further consternate the US's G20 partners, especially China, who will see it as another salvo in the much denied currency war.  However, if they fail to do so, fear of another credit crunch may trigger another US dollar exodus from markets everywhere, and the global 'double dip' recession will be upon us.  It seems that there is no positive alternative, and no way out of the rabbit hole the US has dug for itself and the rest of us.

Perhaps the only thing keeping the floundering juggernaut of global finance afloat is the placebo effect of the actions of its masters who maintain a public image of confidence and certainty about their actions.  If at any time any major player all at once goes bust or pulls their money off the table, everyone else may just decide to cash in.  It seems since the summit, a few players at least, have decided to pocket at least a few of their chips, just in case.